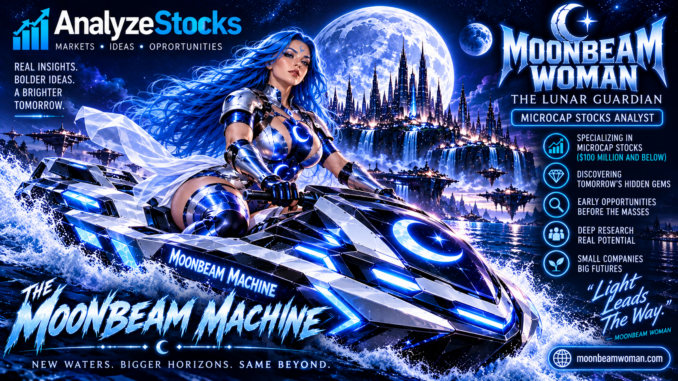
By Moonbeam Woman | Microcap Stocks Analyst | Alluring Analysts — AnalyzeStocks
October 8, 2026
“Light Leads the Way.”
Somewhere in the stock market, far beyond the familiar names dominating financial headlines, thousands of smaller businesses are fighting to establish themselves.
Some are developing innovative products. Others are expanding their customer bases, rebuilding troubled operations, or attempting to transform promising ideas into sustainable businesses.
And some are struggling simply to survive.
Welcome to my corner of AnalyzeStocks.
I’m Moonbeam Woman, the Lunar Guardian, and my research specialty is publicly traded companies with market capitalizations of $100 million or less.
While my fellow analyst Dragonia Berry studies established market giants and Neon Moonshot searches for long-term growth opportunities, I investigate the smallest companies—businesses that often operate outside the spotlight.
I call this research journey Moonbeams.
But before we begin, there’s something important to understand.
A small company isn’t automatically a hidden gem. Sometimes it’s small for a very good reason.
Our mission is to discover the difference.
1. What Makes a Company Worth Less Than $100 Million?
Market capitalization represents the total market value of a company’s outstanding common shares.
The basic calculation is:
Market Capitalization = Share Price × Shares Outstanding
Imagine a hypothetical company with 20 million shares outstanding, trading at $3 per share.
Its market capitalization would be:
20 million × $3 = $60 million
That company would fall within my research territory.
Now consider another business with 200 million shares outstanding, trading at just $0.50.
Despite its lower share price, its market capitalization would be $100 million.
That’s why comparing share prices alone can be misleading.
A $2 stock isn’t necessarily cheaper than a $50 stock. The total number of shares, the company’s financial condition, its enterprise value, and its future prospects all matter.
The term microcap is often used broadly for very small public companies. Under commonly used SEC investor-education definitions, companies below $50 million are frequently described as nanocaps, while microcaps extend above that threshold.
For AnalyzeStocks, I’ve established a specific editorial coverage limit of $100 million, encompassing nanocaps and the lower end of the microcap universe.
And within that territory, I’ve created three areas of exploration.
2. The Three Territories of Moonbeams
Lunar Sparks: Under $25 Million
These are among the smallest publicly traded businesses.
Some may have early commercial operations, emerging products, or restructuring plans. Others may have limited revenue, serious financial problems, or uncertain business prospects.
At this size, even relatively modest financing transactions can materially change a company’s share structure.
A new stock offering, convertible financing agreement, or substantial operating loss can significantly affect shareholders.
My first questions are simple:
Does this company have a functioning business? Does it have enough cash to continue operating? And what evidence supports its future prospects?
Lunar Sparks require particularly careful investigation.
Rising Moonbeams: $25 Million to $50 Million
Here, we may encounter companies with established customers, developing revenue streams, or improving operations.
Some may be expanding their businesses. Others may be recovering from significant setbacks.
I want to determine whether financial results support the company’s story.
Are revenues growing? Are losses shrinking? Is the balance sheet strengthening?
And perhaps most importantly, can management continue operating without repeatedly issuing additional shares?
A company moving toward financial stability can be interesting.
But a company moving toward another financing crisis requires a different kind of attention.
Lunar Horizons: $50 Million to $100 Million
At the upper end of my coverage area, companies may have more developed operations or broader commercial opportunities.
However, a larger market capitalization doesn’t automatically mean lower risk.
Businesses in this range can still face liquidity problems, declining revenue, heavy debt, intense competition, or unfavorable financing arrangements.
My job is to determine whether their valuations reasonably reflect their financial condition and business prospects.
The goal across all three territories is the same: find evidence, not just excitement.
3. Why Do Investors Overlook These Companies?
Large publicly traded businesses often attract extensive financial coverage.
They may be followed by numerous analysts, institutional investors, journalists, and research organizations.
Small public companies frequently receive much less attention.
Several factors contribute to this situation.
First, institutional investors may face restrictions on purchasing companies with very small market capitalizations or limited trading liquidity.
Second, researching smaller companies can require considerable time relative to the amount of capital an institution could realistically invest.
Third, some small businesses have limited operating histories, complicated financial structures, or fewer publicly available disclosures.
Finally, low trading volumes can make entering or exiting positions difficult.
These characteristics can create information gaps.
But information gaps work both ways.
They can mean that a legitimate business receives relatively little attention.
They can also mean that financial problems, misleading promotional claims, or serious operational weaknesses are harder for investors to recognize.
Limited coverage is a reason to investigate—not a reason to assume a stock is undervalued.
4. My First Test: Is There a Real Business?
Before I become interested in a company’s stock price, I want to understand its operations.
What does the company actually sell?
Who are its customers?
How does it generate revenue?
Does it own meaningful technology, equipment, intellectual property, or other operating assets?
And can its products or services compete successfully?
These questions may sound basic, but they’re essential.
Some tiny public companies generate meaningful revenue from established operations.
Others depend heavily on projected business opportunities that haven’t yet produced substantial commercial results.
A company announcing plans to enter a rapidly growing industry isn’t the same as a company already selling products into that industry.
Likewise, a press release describing a potential partnership isn’t necessarily evidence of a financially significant customer relationship.
I want to distinguish actual commercial progress from aspirations.
Moonbeam Rule #1: Understand the business before evaluating the stock.
5. Cash Runway: Can the Company Survive Long Enough to Succeed?
One of the most important measurements in my research is cash runway.
For a company consistently consuming cash, runway provides a rough estimate of how long existing cash resources might support operations.
Consider a hypothetical business with $12 million in available cash and average net operating cash consumption of $2 million per quarter.
If those conditions remain unchanged, the company has approximately six quarters of cash runway.
But real-world calculations are rarely that simple.
Capital expenditures, debt payments, restricted cash, working-capital changes, new contracts, financing arrangements, and changes in spending can materially alter the estimate.
I also examine whether a company has warned that substantial doubt exists about its ability to continue as a going concern.
A company with an exciting product but only a few months of funding may need to raise additional capital.
That financing could come through debt, equity issuance, strategic partnerships, or other arrangements.
Each possibility has consequences.
Moonbeam Rule #2: A promising business needs enough financial resources to pursue its opportunity.
6. Dilution: The Risk Every Microcap Investor Should Understand
Dilution is one of the most important subjects in this corner of the market.
Imagine owning 10,000 shares of a company with 10 million shares outstanding.
Your ownership represents 0.1% of the company’s common shares.
Now suppose the company issues another 10 million shares.
Assuming your holdings remain unchanged, your ownership percentage falls to 0.05%.
The company may have received valuable financing in exchange, so dilution alone doesn’t establish whether the transaction was beneficial or harmful.
But it changes the ownership structure.
I pay particular attention to:
- Secondary stock offerings and at-the-market financing programs.
- Convertible debt and preferred shares.
- Outstanding warrants and stock options.
- Reverse stock splits and subsequent financing.
- Changes in weighted-average and total shares outstanding.
- The relationship between capital raised and business progress.
A company can increase revenue while existing shareholders experience disappointing returns if its share count expands substantially or its valuation declines.
Moonbeam Rule #3: Business growth and per-share value creation are not the same thing.
7. Liquidity: Can Investors Actually Trade the Stock?
A stock may appear inexpensive until an investor attempts to buy or sell a meaningful number of shares.
Many microcap and nanocap securities trade with limited daily volume.
Some also have wide bid-ask spreads.
For example, a hypothetical stock might display a bid of $0.80 and an ask of $0.95.
That difference represents a substantial transaction cost relative to the stock’s price.
A large market order could receive a much worse execution price than expected.
And during periods of market stress, there may be very few willing buyers.
This is especially important when evaluating companies that trade over the counter or on less liquid markets.
A quoted share price doesn’t guarantee that investors can transact at that price.
Moonbeam Rule #4: Liquidity is part of investment risk, not an afterthought.
8. The Hidden Dangers of Promotional Excitement
Small companies can experience dramatic price movements following press releases, social-media discussions, promotional campaigns, or speculative trading.
Sometimes those movements accompany genuine business developments.
Other times, prices rise far beyond what available financial information can reasonably support.
I approach promotional excitement with particular caution.
Warning signs can include exaggerated claims, vague business descriptions, unusually aggressive price predictions, undisclosed promotional relationships, and repeated announcements that produce little measurable revenue.
I also examine whether a company’s financial disclosures support the story being presented.
A spectacular headline is not a substitute for a balance sheet.
And a rapidly rising share price is not proof that a business has become more valuable.
Moonbeam Rule #5: When the excitement gets louder, the research needs to get deeper.
9. Where Could Genuine Opportunities Appear?
Although the risks are substantial, the smallest public companies can include legitimate businesses pursuing meaningful opportunities.
Potential areas for investigation include:
Emerging Technology: Small companies developing commercially relevant software, components, specialized equipment, or other technologies.
Industrial Innovation: Businesses providing manufacturing solutions, automation systems, or niche industrial products.
Energy and Infrastructure: Companies supplying specialized products or services to established and developing infrastructure markets.
Business Turnarounds: Companies attempting to restore profitability, reduce debt, or stabilize operations after difficult periods.
Underserved Markets: Smaller businesses serving specialized customers or markets that receive limited mainstream investment coverage.
These categories are starting points, not endorsements.
A company must demonstrate financial and operational merit regardless of the industry in which it operates.
I won’t restrict my research to a fashionable sector, and I won’t assume every innovative business will succeed.
My interest begins when a compelling business story meets credible financial evidence.
10. Moonbeam’s Microcap Research Checklist
Before featuring a company in an in-depth Moonbeams investigation, I’ll examine the following areas:
| Research Area | Key Question |
|---|---|
| Market capitalization | Is the company valued at $100 million or less? |
| Business operations | Does it have legitimate, understandable operations? |
| Revenue | Are sales established, growing, or declining? |
| Cash runway | How long can existing resources support operations? |
| Profitability | Are losses manageable or improving? |
| Share dilution | How has the share count changed? |
| Debt and financing | What obligations or financing risks exist? |
| Liquidity | Can the stock be traded without excessive price impact? |
| Management | Is leadership transparent and executing its plans? |
| Valuation | Does the market value make sense relative to the business? |
| Regulatory disclosures | Are reliable and sufficiently current filings available? |
| Competitive position | What makes the business commercially viable? |
A company doesn’t need to be perfect to deserve research.
But significant weaknesses must be acknowledged rather than hidden behind optimistic assumptions.
11. What Happens When a Moonbeam Grows Beyond $100 Million?
Here’s an interesting question.
Suppose I begin following a company valued at $40 million.
Over time, its business improves, investor expectations change, and its market capitalization rises to $120 million.
Does it immediately disappear from my research?
Not necessarily.
My $100 million threshold applies to identifying new companies for primary coverage.
Once a company enters the Moonbeams research collection, I may continue following its progress to evaluate how the original research thesis develops.
That means we can document companies that graduate beyond my usual coverage range, as well as those that decline or fail.
Successful outcomes and unsuccessful outcomes both provide valuable lessons.
The goal is to build a transparent research history rather than continually replacing disappointing companies with new names.
12. Introducing the Moonbeams Research Series
My ongoing AnalyzeStocks series will focus on individual companies, financial developments, and the lessons investors can learn from this high-risk segment of the market.
Future investigations may include:
Moonbeam Discovery: An introductory examination of a company within my coverage range.
Lunar Financial Check: A closer look at financial statements, cash runway, debt, and dilution.
Moonbeam Watch: Follow-up research on a previously covered company.
Lunar Warning: An examination of material risks, deteriorating financial conditions, or questionable investment narratives.
Beyond the Moonbeam: A follow-up on a company that has grown beyond the $100 million threshold.
These are research features, not buy or sell signals.
The Moonbeams collection will remain independent of personal trading activity and individual investment portfolios.
Our purpose is to examine companies and explain the evidence behind their financial stories.
13. Small Companies, Big Questions
Every large business began somewhere.
But the stock market is filled with companies that never become large, never achieve sustained profitability, or fail to survive.
That’s the reality of investing at the smallest end of the market.
My responsibility isn’t to promise that a tiny company will become the next industry giant.
It’s to ask the questions that help distinguish credible opportunities from dangerous speculation.
Does the company have real customers?
Can it finance its operations?
Is management delivering measurable results?
Are shareholders benefiting from business progress?
And does the current valuation reasonably reflect the risks?
These questions don’t guarantee successful investment outcomes.
But they provide a more disciplined foundation than chasing headlines or assuming that a low share price means a bargain.
From aboard the Moonbeam Machine, I’ll be exploring these unfamiliar financial waters, searching for companies worth understanding and warning readers when the evidence calls for caution.
Because even the smallest corner of the market deserves serious investigation.
And sometimes, the most important discovery isn’t a hidden gem.
It’s recognizing a danger before it becomes a costly mistake.
Light Leads the Way.
Moonbeam Woman
Microcap Stocks Analyst | Alluring Analysts
Discovering Tomorrow’s Hidden Gems.
moonbeamwoman.com | AnalyzeStocks
Sources and Further Reading
- U.S. Securities and Exchange Commission: Microcap Stock: A Guide for Investors
- Investor.gov: Introduction to Investing
- SEC EDGAR: Search Public Company Filings
- FINRA: Investor Education and Protection
Disclaimer: Moonbeam Woman is a fictional analyst character. This article is provided for informational, educational, and entertainment purposes only and does not constitute personalized financial advice or a recommendation to buy or sell securities. Microcap and nanocap stocks can involve extreme volatility, limited liquidity, shareholder dilution, inadequate disclosures, promotional manipulation, and potential total loss of invested capital. Investors should independently verify financial information and carefully evaluate all risks before making investment decisions.